Brooklyn Co-ops vs Condos: Which Listing Type Fits You in 2026?
The Brooklyn co-op vs condo question matters more than most buyers expect, because two listings can look nearly identical on a screen and behave completely differently the moment you make an offer. The label on the listing matters as much as the square footage. A co-op and a condo are different legal purchases. Lenders, boards and future buyers treat them differently. Understanding those differences before you start touring saves weeks of wasted effort and, on the closing side, can mean a meaningful difference in out-of-pocket cost.
The Core Difference: Shares Versus Real Property
When you buy a condominium you are purchasing real property. You own the unit, your name goes on a deed, and that deed is recorded. You also own a share of the building's common elements.
When you buy a co-op, you are purchasing shares in the cooperative corporation that owns the building. Those shares come with a proprietary lease that gives you the right to occupy a specific apartment. In effect, you do not buy an apartment. You buy a piece of the entity that owns the building and the right to live in one unit within it.
That single structural difference drives almost everything else: closing costs, financing, board approval, building rules, and how quickly the apartment sells when you decide to move on.
Closing Costs: The Gap Shows Up Early
Closing costs are where the two paths diverge fastest. For a financed condo purchase, total buyer closing costs typically run 4% to 6% of the price. Co-ops avoid the recording tax and title insurance, so co-op closing costs typically run 1% to 3%.
| Cost factor | Condo | Co-op |
|---|---|---|
| Typical total buyer closing costs, financed purchase | 4% to 6% of the purchase price | 1% to 3% of the purchase price |
| Recording tax | Applies | Typically avoided |
| Title insurance | Typically part of the transaction | Typically avoided |
| What the buyer receives | Real property, with a deed | Shares in the corporation plus a proprietary lease |
Because these are percentages of the purchase price, the gap between the two ranges grows as the price climbs. Before you commit to either path, ask your lender and your attorney for an itemized written estimate for the specific unit you are considering, since individual buildings and lenders vary.
Purchase Price and Entry Cost
Co-ops tend to be less expensive than condominiums. Co-ops are common in Brooklyn's historic building stock and may offer a lower entry price, though rules and board reviews can be stricter. Market commentary from a 2026 Brooklyn rent-versus-buy analysis frames the same pattern another way: condos cost more upfront, while co-ops come with lower entry prices and board approval requirements.
For a buyer stretching to afford a particular neighborhood, that price difference can be the deciding factor. The trade-off is that you are accepting a more controlled purchase process and a smaller pool of future buyers. The lower number on the listing is real, but it is not free.
Board Approval and Building Rules
Co-op purchases require board approval, and board reviews can be strict. A co-op board typically reviews your financial picture in detail, not just your ability to get a mortgage. That often means submitting financial statements, references, and supporting documentation, and in many buildings sitting for an interview.
Each co-op sets its own standards, and those standards differ from building to building. Rather than assuming what a given board will accept, verify the requirements directly with the listing agent or managing agent before you make an offer. Knowing the building's expectations early tells you whether the purchase is realistic for your situation.
Condo purchases do not typically involve a personal board interview. Buying into a condo is generally the easier of the two paths, which is one reason condo listings attract buyers who want a more predictable process or who need flexibility in how they hold or use the property.
Financing a Co-op Versus a Condo
Financing a co-op is more building specific than financing a condo. Because co-op ownership is structured around shares and a proprietary lease rather than a deed, lenders evaluate the building as well as the borrower, and their standards differ from one another. Two lenders can give you different answers about the same building.
Practical steps that help: get pre-approved before you tour, ask your lender early whether they will lend in a specific co-op building, and confirm the building's own purchase requirements in writing. If a lender declines a building, that is useful information before you spend money on inspections and attorney review, not after.
Resale Liquidity and Long-Term Value
The exit is where the two types separate again. Condos cost more upfront but appreciate more reliably and have stronger resale liquidity. Co-ops have lower entry prices, but board approvals can slow or complicate a sale, because every buyer who comes after you has to clear the same review you did.
In practical terms, a condo tends to be easier to sell and easier to sell quickly. A co-op can sit longer while applicants are vetted, and a rejected buyer restarts the process for everyone. If your plans include a possible move within a few years, weigh exit speed alongside the lower purchase price.
Which Type Tends to Suit Which Buyer
There is no universal right answer, but the patterns are consistent enough to be useful:
- Buyers focused on the lowest possible entry price and the lowest closing costs often find more room in co-ops.
- Buyers who want the simplest, most predictable purchase process often prefer condos.
- Buyers who may need flexibility on timing, or who expect to sell within a few years, often weigh condo resale liquidity heavily.
- Buyers who value a building with a formal review process and defined standards may be comfortable in a co-op, provided they can meet the board's expectations.
- Buyers comparing two specific apartments in the same neighborhood should compare the all-in cost of each, including closing costs and monthly carrying costs, rather than the list price alone.
What Brooklyn's Building Stock Means for Your Search
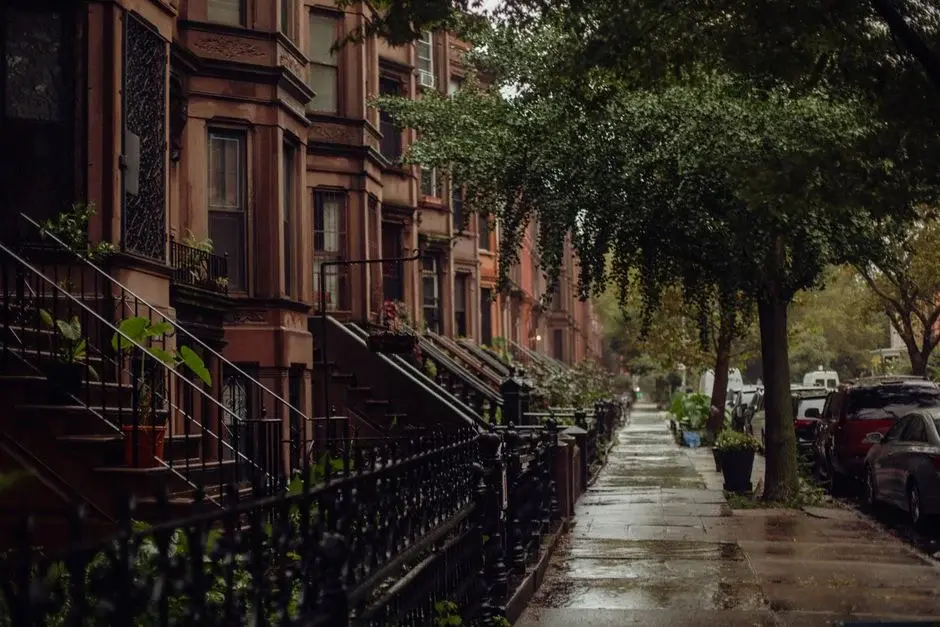
Co-ops are common in historic stock, which matters in a borough with a deep inventory of older apartment buildings. If you are drawn to prewar layouts and established buildings, co-op rules and board review will come up often in your search.
Condo listings show up across a wider range of building types and are frequently the format associated with more recent construction.
The result is that your neighborhood preference and your ownership preference can pull in different directions. It helps to decide which one you are less willing to compromise on, whether that is an area like Brooklyn Heights or a specific ownership type, before you start touring, so you are not falling for apartments you cannot realistically buy.
Questions to Ask Before You Commit
Bring this list to every showing and follow up in writing:
- Is this unit a co-op or a condo, and does the purchase require board approval?
- What is the monthly carrying cost, and what does it include?
- What are the estimated total closing costs for this specific purchase?
- Will my lender finance in this building, and are there any building-level financing requirements I should know about?
- What building rules should I review before making an offer?
- How long have comparable units in this building taken to sell recently?
Making the Decision
Start with your timeline, then your budget, then your tolerance for process. If you plan to stay for years and want the lowest entry cost, a co-op deserves serious consideration. If you want the smoothest purchase and the easiest exit, a condo usually costs more but delivers more predictability.
The most reliable next step is a side-by-side comparison of real listings in the neighborhoods you actually want, run through the numbers above rather than through list price alone. That comparison, done with a local agent who knows which Brooklyn buildings require what, will tell you more than any general rule.
Frequently Asked Questions
What is the downside of a co-op?
The main downside is control. A co-op board reviews and must approve your purchase, rules can be stricter than in a condo, and the same review applies to whoever buys from you later. That can slow a resale and shrink your buyer pool. You also receive shares and a proprietary lease rather than a deed.
Why are co-ops cheaper than condos?
Co-ops tend to be less expensive than condominiums, and co-ops are common in Brooklyn's historic building stock, which often means a lower entry price. Stricter rules and board review narrow the pool of eligible buyers, and that can hold pricing below comparable condos. Closing costs also run lower, typically 1% to 3% on a financed purchase.
Is it easier to buy a condo or a co-op?
Condo purchases are generally the more straightforward path, since they do not typically involve a personal board interview and you are buying real property with a deed. Co-ops require board approval and a financial review, and each building sets its own standards. Verify the specific requirements with the listing or managing agent before making an offer.
Do co-ops appreciate as well as condos?
Market commentary indicates condos appreciate more reliably and have stronger resale liquidity, while co-ops offer lower entry prices with slower, more conditional exits. That does not mean co-ops never gain value, but the resale process is less fluid. If appreciation and quick resale matter most to you, condos generally carry the advantage.
How much are closing costs on a co-op versus a condo in Brooklyn?
On a financed condo purchase, total buyer closing costs typically run 4% to 6% of the price. Co-ops avoid the recording tax and title insurance, so they typically run 1% to 3%. Because these are percentages, the dollar gap widens as price rises. Ask your lender for an itemized estimate for the specific unit.
Brooklyn Co-ops vs Condos: Which Listing Type Fits You in 2026?Brooklyn Real Estate2026-09-30T17:42:14+00:00